For your organization
Offer financing without building the system.
- Published rules and defined responsibilities
- Participant records and repayment visibility
- Operations designed for your structure

Community financing infrastructure
People, local businesses and community organizations can do more together. We are building the infrastructure to connect them through shared finance, saving and financial education, so more value stays close to home. Starting with a small cooperative pilot in Siargao.
Product in development. The first cooperative-operated member program is in preparation. Access will depend on cooperative membership and the program's adopted eligibility rules.
A sample of what a participating organization would see.
Illustrative product preview · example data
Who this serves
Families, workers, vendors and local organizations. Different needs, connected lives, and a shared interest in more affordable finance without depending on exploitative lenders.
Photographs are illustrative and do not depict actual members or borrowers.
Why Kapitala
The relationships are already there. The tools to connect shared capital, responsible borrowing and financial learning often are not.
An urgent bill, a livelihood that needs investment, a neighbour willing to help. Kapitala is being built to connect those needs and contributions through organized community finance. Businesses are one route in, alongside cooperatives and other local institutions.
Our aim is more affordable borrowing, a habit of saving and better financial choices, with less dependence on exploitative lenders. The planned software model is free for small pools; the thresholds and later fees are still being worked out.
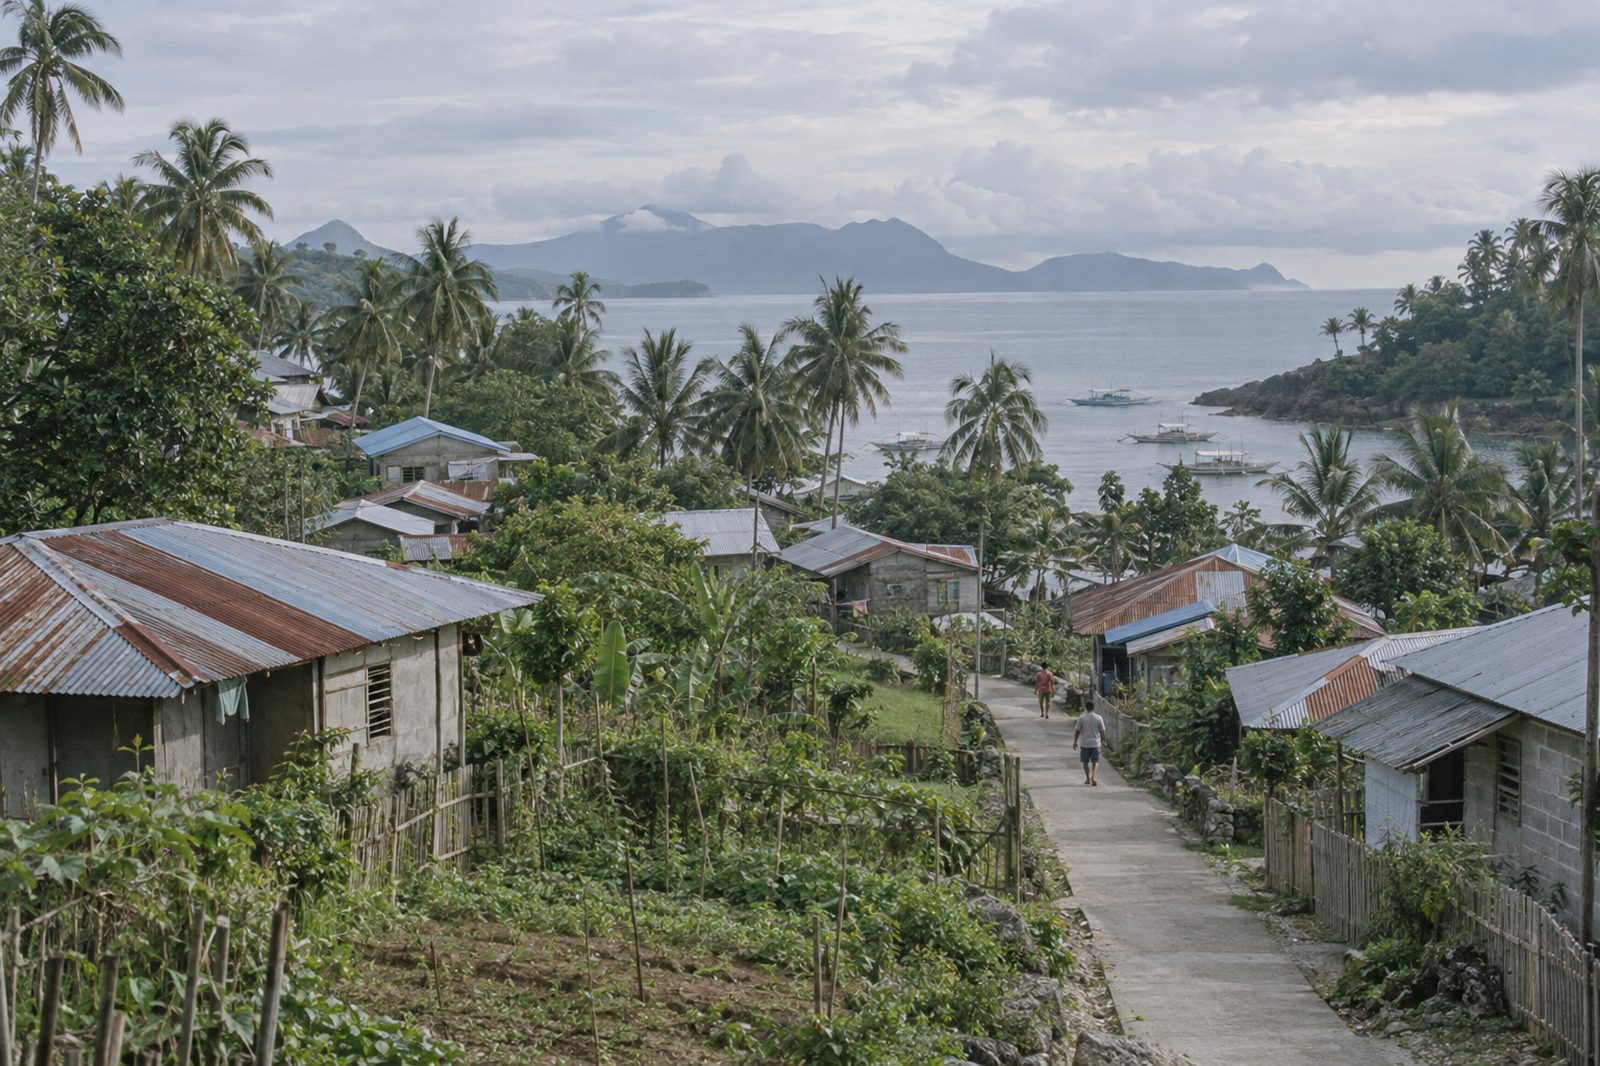
Financing that stays inside the community it comes from.
Connected, without being exposed
Digital access is a starting point. Useful finance, understandable choices and control over personal information are the goal.
We are researching Midnight's fourth-generation blockchain approach, including selective disclosure: sharing only what an interaction needs, or proving a defined fact without revealing the underlying private record. This is a future direction, not a live Kapitala integration or a requirement for the small first pilot.
One model, three roles
A person can be both contributor and borrower. The lawful structure of each pool sets the specific rights and responsibilities.
For your organization
For people contributing capital
Funding rights and risks depend on the legal instrument. No returns are promised.
For borrowers
Kapitala is not an open matching marketplace or a direct source of loans.
How the pieces connect
Capital supports a member's need. Repayments can support the next. The app is one part of the infrastructure that makes this manageable, alongside the rules and operating structure.
Under the applicable rules and requirements, the organization sets the program up and supplies or gathers the capital.
Members and borrowers use the tool to understand terms, schedules and recorded events before committing.
Rules are applied consistently and the record can be reviewed. Repayments return to the pool, with costs, interest and losses allocated under published rules.
Transparent by design
Code should apply the rules consistently, and members should be able to check the record. Technology supports accountability; it does not remove the risks or replace responsible operators.
Understand how rules and responsibilities should work, including what is still being finalized.
Who does what in each model: operator, contributor, borrower, and where funds sit.
How recorded outcomes can be checked, including what cannot be verified today.
Where we are going
Prepare the first program in Siargao, learn from a small pilot, then help other businesses, cooperatives and community organizations adopt it. Our long-term direction is open-source, collaborative infrastructure for the Philippines.
Common questions
The documentation covers each of these in full.
Kapitala is infrastructure, not a bank or a lender anyone can borrow from directly. An app makes it easier to use, but financing runs through a participating organization under its lawful rules. We are starting with Kapitala Credit Cooperative. There are no bank deposits or guaranteed returns.
No. Borrowing happens through an organization you already belong to, such as your employer or your cooperative, and only if you are eligible under its rules. Kapitala is not an open marketplace.
The published rules do. Outcomes follow the rules rather than anyone's judgement on the day, and the same rules apply to every participant. There are no manual approvals or exceptions.
Hardship handling is written into the rules in advance. It is time limited and applies automatically rather than being negotiated case by case. Losses are possible, and the rules state how they are shared.
No. The intended member experience uses pesos, not crypto. Audit technology is being tested in the background to make records checkable. There is no token offer and no token is required to take part.
Read. The product is in development, so there is no enrolment, no deposit and no loan application. Every article states what exists today and what is still planned.
Product in development. No enrolment, deposits or loan applications.